You've built a fintech product people want to sign up for. Then KYC kicks in, and some of those signups disappear before they ever fund an account. This guide walks through the KYC onboarding process step by step, so you know where users drop off and why.
TL;DR
- KYC onboarding is the identity check every fintech and bank runs before a customer can transact.
- The process breaks into distinct steps: data collection, identity verification, screening, and risk scoring.
- Digital onboarding tools can cut this down to minutes, but only when the flow is built around the user.
- The biggest challenges are drop-off, false rejections, and keeping compliance and customer experience in balance.
Here's a stat that's worth your attention. 70% of financial institutions lost clients in the past year to slow or clunky onboarding, according to Fenergo's 2025 Financial Crime Industry Trends Report. The KYC step of onboarding isn't a footnote. It's often the reason a signup never becomes a customer.
What is KYC Onboarding?
Before a bank or fintech lets someone open an account or move money, it needs to confirm who that person actually is. KYC onboarding folds identity checks, document verification, and risk screening into one flow at signup.
For the regulatory side of this, what KYC is and how it ties to AML compliance gets covered in a separate guide. This article stays focused on the onboarding process itself: the steps, the friction points, and how fintech onboarding teams keep compliance and customers both satisfied.
Every fintech and bank runs a version of this same flow. What changes is how much friction gets added, and how much of it needs to be there.
Some of that friction comes from regulation. A good amount of it comes from product decisions nobody revisited after launch. An extra form field, a document type that rarely gets accepted on the first try, a status page that leaves the user guessing. No regulation requires any of that.
The KYC Onboarding Process Step by Step
Most KYC process steps follow the same general order. It doesn't matter much if the customer is opening a checking account or signing up for a crypto wallet.
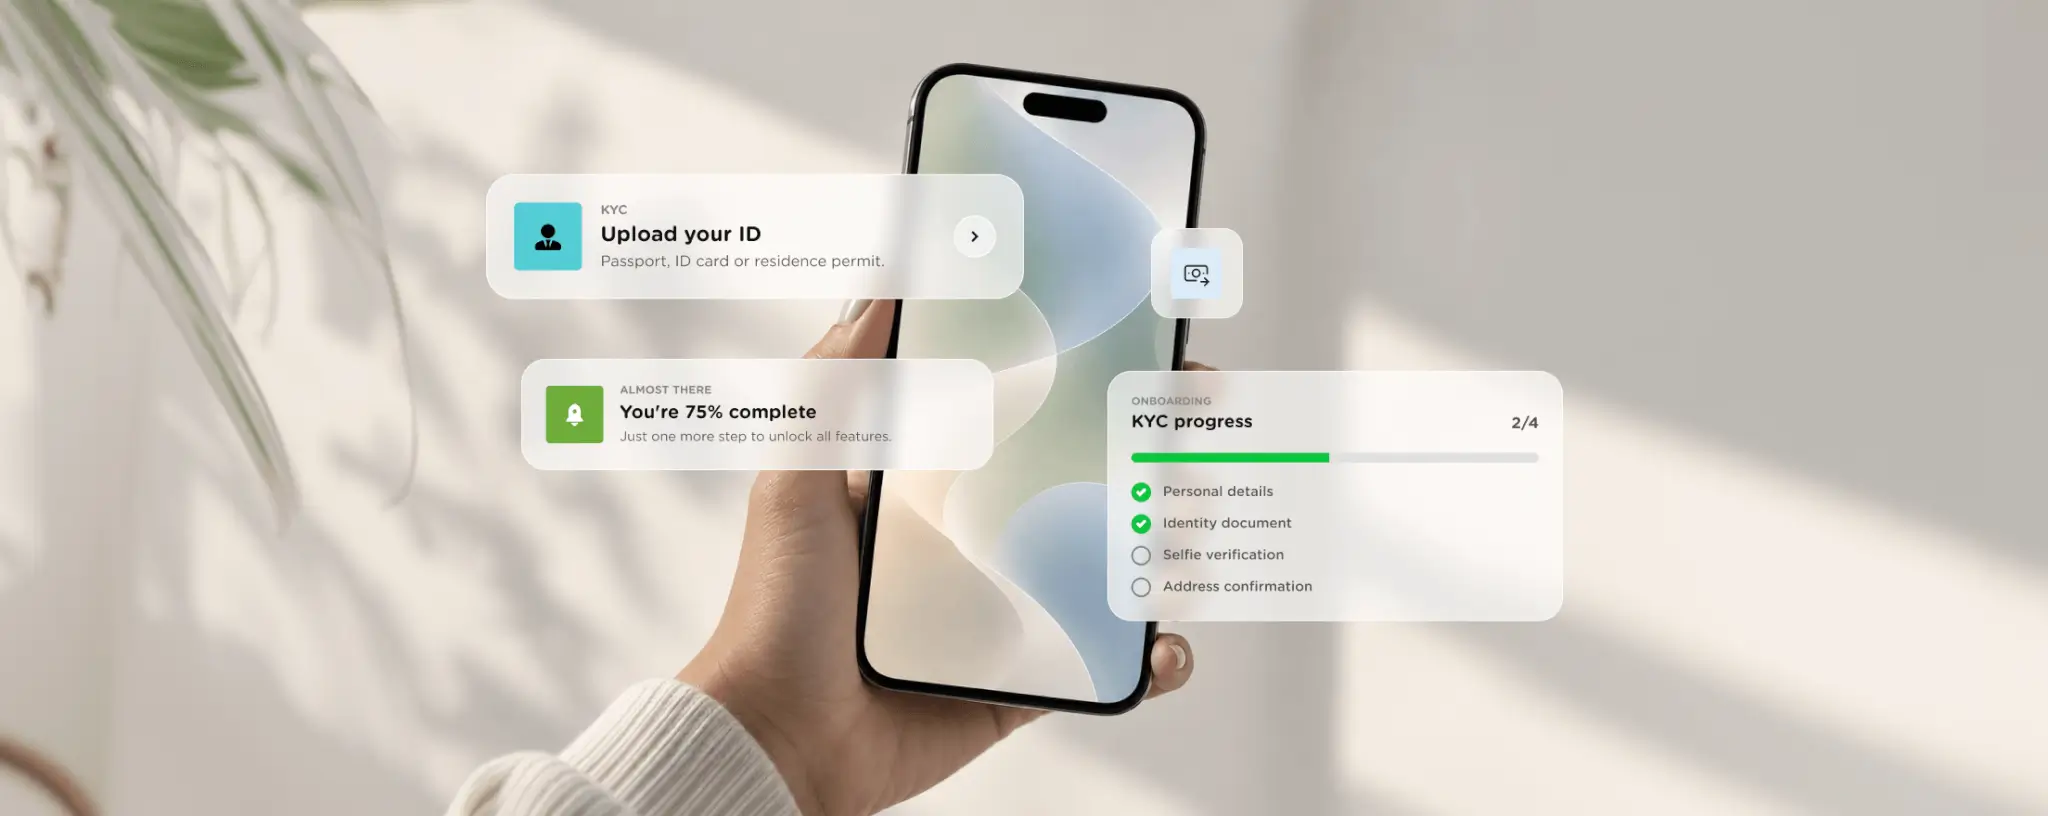
1. Data collection. The customer submits basic details: name, date of birth, address, and sometimes a tax ID. This is the shortest step, and also the one users abandon fastest if the form asks for too much too soon.
2. Document verification. The customer uploads a government ID, and the system checks it for authenticity. A blurry photo or an expired document stalls the process here, which is why this step causes a large share of onboarding drop-off.
3. Identity verification. A liveness check, usually a selfie compared against the ID photo, confirms the person applying is the person in the document. This step catches synthetic identities and stolen documents.
4. Screening. The customer's name gets checked against sanctions lists, politically exposed persons databases, and adverse media. This part of the AML KYC client onboarding process runs in the background and rarely needs input from the user.
5. Risk scoring. Based on the data collected, the system assigns a risk level. Low-risk customers usually pass straight through. Higher-risk customers, larger transactions, or unusual account activity get flagged for extra checks.
6. Approval or escalation. Low-risk applications get approved automatically, often within minutes. Anything flagged goes to a human compliance analyst for manual review. That single step can add days to the whole timeline.
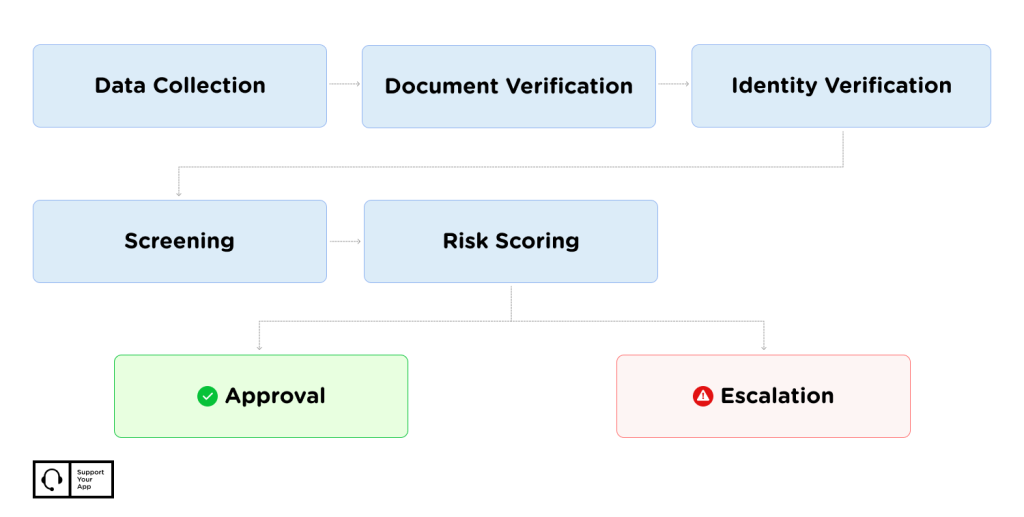
Skip any of these steps and a regulator will eventually notice. Overlook the design work around them, and your customers spot first, usually by closing the app halfway through.
Digital Onboarding in Fintech & Banking
Most banks now offer digital onboarding for financial services customers can complete entirely on a phone, no branch visit required. The customer onboarding process in banking used to take weeks. Today the digital version can finish before the coffee gets cold, for low-risk applicants at least.
Digital onboarding in banking now means the entire journey, from data entry to identity verification, happens within a single app or browser session. Yet not every institution has fully committed to that model, and the gap shows up fast. Banks that still route flagged applications to a call center or branch tend to lag, since those handoffs slow approval times.
Building digital onboarding for financial services means balancing speed with every regulatory box that still needs checking. It's a real tension: move too fast and compliance suffers, move too carefully and users drop off. Client onboarding in banking that's designed mobile-first tends to convert better than a flow simply ported over from a desktop web form. Smaller fields, native camera capture, and visible progress all help, since each one reduces how many people quit partway through.
Banking teams handling digital customer onboarding are also under pressure to move faster without cutting corners on the checks themselves. That tension sits at the center of almost every onboarding redesign.
Client onboarding banking flows that succeed usually share one trait. They ask only for what the current step needs, instead of front-loading every data point before the user has seen any value.
Identity Verification in Onboarding
This step is where most of the actual friction lives, and where most fraud gets caught. It's worth treating as its own design problem, separate from the rest of the KYC flow. A typical identity verification for digital onboarding step asks for a photo ID, then a selfie or short video, then runs both through matching software. Camera quality, lighting, and document type all affect how often this step fails on the first try.
KYC Onboarding flows that let users retry a failed scan recover far more applicants than flows that reject silently. Clear, specific guidance helps: move closer, reduce the glare, try the other side of the card. Vague error messages just leave the user guessing, and guessing is where people give up.
Some products now offer a middle ground: limited account access before identity verification finishes, with full functionality unlocked once the check clears. It doesn't remove the requirement. It just moves the moment of friction to a point where the user is more invested in staying.
Balancing Compliance and Customer Experience
Compliance and customer experience often get treated as opposing goals. One team wants more checks, the other wants a shorter form. In practice, the flows that actually work treat both as the same design brief.
The fix usually isn't fewer checks. It's better sequencing. Collect information gradually instead of all at once, and give users a clear reason for each request. Show real-time status instead of a silent waiting screen.
Support matters here too. A user stuck on document upload at 11 p.m. needs a fast answer, not a three-day email thread. That's where fintech customer service built around onboarding earns its keep.
Getting this balance right isn't optional. It's the difference between a KYC flow that protects the business and one that bleeds it dry, one abandoned application at a time. Most teams don't notice the second one until the drop-off numbers force a conversation.
Common KYC Onboarding Challenges (and How to Solve Them)
Drop-off at document upload. This is usually the single biggest leak in the funnel.
Fix: accept a wider range of document types, add real-time image quality feedback, and let users pick up where they left off instead of restarting.
False rejections. Legitimate customers get flagged because of a lighting issue, a name mismatch, or an outdated database entry.
Fix: build a fast manual review path for anything the automated system flags, so a false positive costs minutes, not days.
Slow manual review. Once an application escalates to a human, timelines stretch fast.
Fix: triage escalations by risk level, and route only genuinely high-risk cases to your most experienced analysts.
Fintech onboarding built for one region. A flow tuned for one country's ID formats and address structures often breaks for customers elsewhere.
Fix: test the flow against every document type and address format your actual customer base uses.
Volume spikes. A marketing push or a seasonal signup wave can overwhelm a manual review queue overnight.
Fix: build a plan for scaling reviewers on short notice, whether that means cross-training staff from other teams or bringing in specialist KYC outsourcing to cover the gap without slowing down approvals.
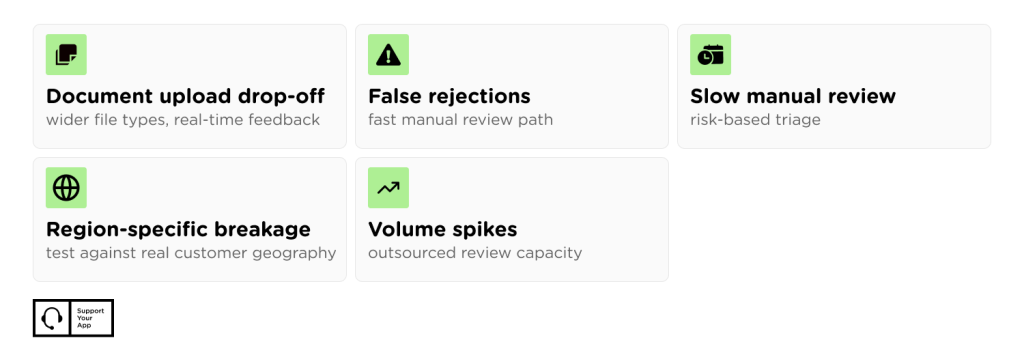
None of these problems need a full rebuild of the KYC process. Most come down to fixing the one step that's costing more customers than it's protecting. Pull your own funnel data before assuming which step that is. Teams often guess document upload when the real leak sits earlier, at the initial data form.
Summary
If your team is losing customers somewhere in this process, that's worth a second look. It's an even clearer signal if reviewing every flagged application in-house is stretching people thin. SupportYourApp handles fintech customer support and KYC-adjacent workflows across 60+ languages, built for teams that need compliance and speed at the same time.